
Reconstruction begins when the emergency condition is controlled and the affected scope is understood well enough to restore the building. It may follow extraction, drying, cleaning, remediation, and selective demolition. The rebuild is not automatically part of the mitigation estimate.
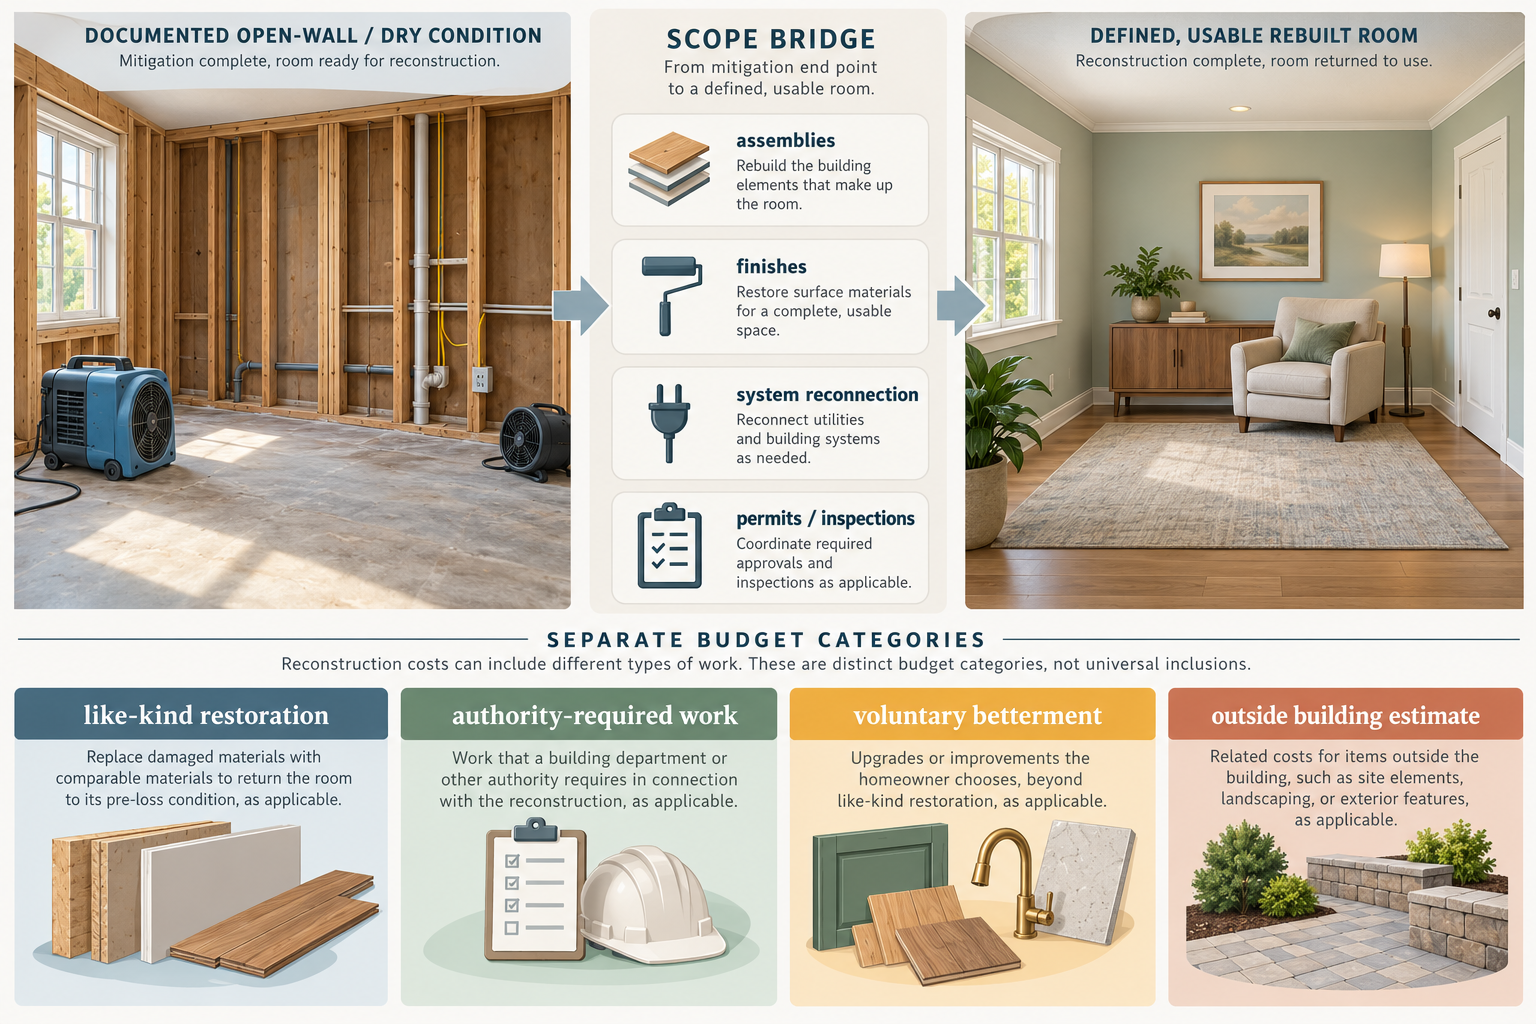
Build the scope from the condition
Reconstruction may include framing, insulation, drywall, ceilings, trim, flooring, cabinetry, paint, fixtures, and reconnection of electrical, plumbing, or HVAC systems. The exact list depends on what was removed or damaged and what can be safely retained.
Ask the contractor to distinguish observed damage, assumed damage, and work that requires an opening or later inspection. Hidden conditions can create supplements or change orders; they should not be disguised as a fixed certainty.
Main cost drivers
The rebuild cost depends on affected area and assemblies, structural work, finish level, specialty materials, access, labor availability, contents, permits, inspections, code-driven changes, and the need to work around a partially occupied or protected building. A restoration rebuild can also have different mobilization and coordination costs from an ordinary remodel.
There is no single national reconstruction price or universal percentage that identifies a total loss. A whole-home remodel article is not a substitute for a recovery-level scope based on the actual damaged assemblies.
For a dated Canadian trend signal, Verisk’s Q1 2026 analysis compared modelled residential reconstruction costs in January 2026 with January 2025. It reported increases of 4.2% for its 1,000-square-foot model, 4.4% for 2,000 square feet, 4.0% for 3,000 square feet, 3.7% for 4,000 square feet, and 2.4% for 5,000 square feet. These are modelled year-over-year changes, not absolute repair prices, restoration bids, or a quote for a specific property. They help explain why an older replacement-cost estimate may need updating; a local, damage-specific scope is still needed.
System handoffs
The rebuild may need specialized plumbing, electrical, HVAC, roofing, structural, window, or finish trades. Keep source repair, restoration, and permanent replacement visible. A contractor coordinating several trades can be convenient, but the quote should still say who owns each part of the work.
Permits, code, and payment
Local permits and inspections can affect both price and sequence. A current-code requirement may be separate from restoring like-kind materials, and insurance may treat it separately. Compare the contractor’s scope with the insurer’s scope, policy limits, deductible, and valuation without assuming that one document controls the others.
Before signing, ask what condition marks the transition from mitigation to reconstruction, which items are included, what happens when hidden damage is discovered, and how final inspection or reoccupation will be handled.
Keep four budget lines visible: like-kind restoration of damaged building work, authority-required work if any, voluntary homeowner-selected betterment, and costs outside the building estimate such as contents handling or displacement. The applicable authority determines requirements; the actual policy and insurer determine coverage and payment; neither question is answered by the contractor’s total alone.
If the insurer has issued repair proceeds but a mortgage servicer must release them, compare the release steps with the reconstruction payment schedule before relying on that cash. The mortgage-proceeds guide covers that timing question separately from the rebuild estimate.
Make matching and access visible
Replacing a damaged finish may require extending work into an adjacent area so the result is consistent. Limited access may require temporary removal of cabinets, fixtures, or unaffected materials. Ask whether matching, protection, furniture movement, cleaning, and final touch-ups are included.
A reconstruction estimate should describe the finished result
Start with the mitigation handoff. Ask whether the property is dry, cleaned, stripped to a defined boundary, and ready for the proposed rebuild. Request the rooms and assemblies released to reconstruction, photographs, removed-material records, unresolved conditions, and any specialist reports. A rebuild estimate made before that record exists may rely on assumptions that change later.
Then define the finished result. Does the estimate restore like kind and quality, match adjacent finishes, reconnect systems, clean the work area, and leave the room usable? Does it include furniture movement, protection of unaffected work, temporary access, testing, commissioning, permits, inspections, and final touch-ups? Two totals can differ because they stop at different end conditions.
Main cost layers
The reconstruction price may include framing or structural work, insulation, drywall, subfloor, floor finish, cabinets, trim, doors, windows, paint, fixtures, plumbing, electrical, HVAC, roofing, exterior finishes, debris cleanup, and trade coordination. Design, engineering, permits, inspections, temporary protection, storage, and project administration can add separate cost.
The finish level also matters. Replacing a damaged floor with a readily available material is a different decision from matching a discontinued or specialty finish across adjoining rooms. Reconnecting a system can require work outside the visibly damaged area. A quote should identify where matching, code compliance, or access expands the footprint.
Hidden conditions and change orders
Reconstruction often follows removal, so some conditions are unknown at the time of the first bid. Ask what evidence triggers a supplement, who documents it, how the price is calculated, and whether work pauses for approval. A contingency or allowance can make uncertainty visible; it should not be used to hide an unsupported certainty.
Keep like-kind restoration, authority-required work, voluntary betterment, and unresolved conditions separate. A homeowner-selected layout change or premium finish may be worthwhile, but it should not be blended into the amount needed to restore the damaged building.
Insurance and handoffs
The contractor’s scope, the adjuster’s estimate, and the policy’s valuation or coverage terms serve different purposes. Deductible, limits, exclusions, endorsements, code treatment, and payment timing can affect the homeowner’s cash flow. Ask the insurer which documentation it needs and ask the contractor which work remains outside the claim scope. Neither professional should be asked to decide the other’s authority.
Compare estimate boundaries before comparing totals
| Estimate boundary | What to identify | Why the price may differ |
|---|---|---|
| Starting condition | Whether the room is dry, cleaned, demolished to a known boundary, and released for rebuilding | One bid may include removal or preparation that another assumes is complete |
| Included rebuild work | Assemblies, quantities, material quality, finish, trade work, and system reconnection | The same room can have different quantities or a different finished condition |
| Project support | Protection, access, moving, design, permits, inspection, cleanup, and coordination | These costs may sit outside a narrowly priced installation scope |
| Unknown conditions | Allowance, contingency, concealed damage, and approval before added work | A fixed total can exclude changes that another estimate makes visible |
| Completion point | Testing, touch-ups, debris removal, records, and room return | A rough installation price is not comparable with a completed, usable space |
For example, an estimate that starts after demolition and ends at drywall installation is not necessarily cheaper than one that includes safe removal, dust protection, finish work, system reconnection, and closeout. It may simply cover fewer stages. Ask each contractor to state the condition assumed at the start and promised at the end, then place omitted work and allowances beside the headline price. This reveals whether the difference comes from rate, quantity, quality, or scope.
Before signing, ask:
- What condition did mitigation leave?
- What building and system work is included?
- Who handles permits, inspections, and specialist trades?
- What is excluded or assigned elsewhere?
- What matching and protection assumptions apply?
- What happens when concealed damage is found?
- What event marks practical completion?
Reconstruction cost is best understood as the price to move from a documented mitigation end condition to a defined usable result. That is more useful than a whole-home average or a single percentage of the original loss.
Selections and finish-level decisions
Many reconstruction disputes are really scope mismatches. A quote may restore a damaged floor, while the homeowner expects matching flooring through adjoining rooms. One estimate may include standard cabinets, while another includes custom work. One may reconnect a fixture, while another includes a layout change. Put those choices beside the affected room and identify whether they are required to restore the prior condition, required by an authority, or selected by the homeowner.
Ask when selections are due and what happens if a material is unavailable. Delayed selections can extend temporary housing, storage, and trade scheduling. A substitution may change appearance, performance, price, or approval requirements, so the change should be recorded before installation where practical.
The completion description should cover function as well as appearance: systems connected, permits and inspections addressed, protection removed, debris cleared, contents returned or handed off, and unresolved items listed. A visually finished room is not necessarily a completed project if a required specialist or authority decision remains open.