
A damaged home may not be allowed to return to its former physical condition in exactly the same way. A local permit, adopted building code, floodplain rule, or other requirement may add work to a repair or reconstruction project. That can change design, material, inspection, schedule, temporary-housing, and construction costs.
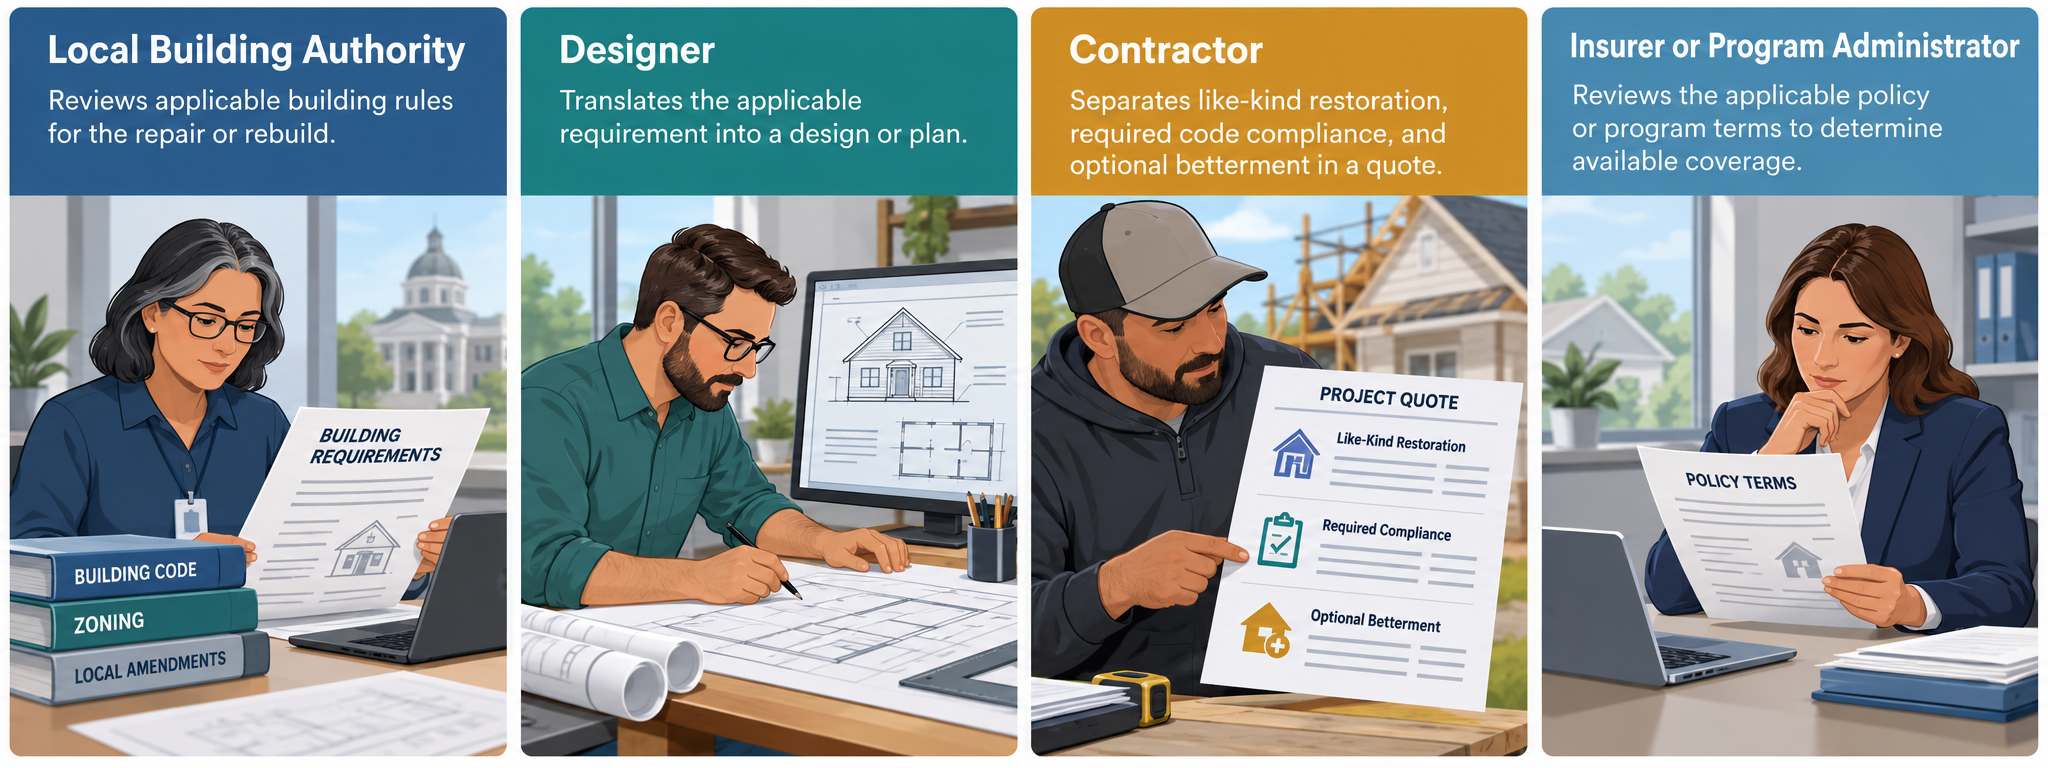
The phrase “bring it to code” is not enough to establish what work is required or who will pay. A local authority decides applicable code and permit questions; the insurer decides coverage under a policy; the contractor prices a defined scope; and the homeowner decides whether to add optional work. These are related decisions, but they are not interchangeable.
Identify the decision before pricing the upgrade
Ask the building official or floodplain administrator what rule applies to this property and project. Request the written determination, permit condition, drawing requirement, inspection step, or other record that creates the proposed work. Then ask the designer or engineer to show how the requirement changes the plans and ask the contractor to price that work separately from ordinary repair.
The answer can depend on location, building type, use, extent of damage, permit scope, prior improvements, floodplain status, and the rule currently adopted by the jurisdiction. A contractor’s allowance, insurer’s estimate, another property’s repair percentage, or an online article cannot establish the local trigger.
Keep at least four cost lines visible:
| Cost line | What it describes | Who can answer the main question |
|---|---|---|
| Like-kind restoration | Work to repair or replace the damaged property within the defined pre-loss scope | Contractor or qualified designer describes the physical work; insurer interprets coverage |
| Required compliance | Work a local authority requires for approval of this project | Authority identifies the rule and permit condition; designer and contractor translate and price it |
| Optional betterment or resilience | A homeowner-selected finish, layout, system, or future-risk measure beyond the stated requirement | Homeowner weighs the preference and price; contractor prices the option |
| Funding and administration | Policy or public-program payment, plus any eligible government administrative cost | Insurer or program administrator determines its own terms; government reimbursement is not automatically household money |
A single physical change can touch more than one line. For example, opening a wall for a required electrical change may reveal separate water damage. Show each reason and amount so a new condition, mandatory measure, and optional upgrade do not disappear inside one “code” subtotal.
NFIP substantial damage is a local floodplain determination
FEMA describes a baseline under the National Flood Insurance Program (NFIP) for participating communities in Special Flood Hazard Areas: when repair costs equal or exceed 50% of the building’s pre-damage market value, the structure is substantially damaged and must meet current local floodplain standards. FEMA’s guide discusses repair-cost inputs such as labor, demolition and disposal, contractor overhead, utilities, elevation or floodproofing, site preparation, code compliance, and finishes. The market-value comparison is for the structure, not land or site improvements.
This is a floodplain-management baseline, not a national insurance payout rule, a universal repair-versus-rebuild test, or a determination that an insurer owes for the work. The community may have a stricter threshold or cumulative repair rule. Local officials determine the applicable repair cost and value consistently under local authority. Ask which rule is adopted, how the affected structure is valued, what costs are included, and who issues the written determination. FEMA’s Substantial Damage Quick Guide provides the bounded NFIP explanation; the local decision controls the project.
A substantial-damage finding can require compliance work even if the building remains physically repairable. It does not by itself say whether repair is economical, whether a homeowner’s policy calls it a total loss, or whether a particular insurance claim qualifies for a payment. Compare those questions using the actual determination, policy, and reconstruction scope.
Keep three NFIP decisions distinct
Flood claims can bring several NFIP terms into the same conversation. They refer to different decisions:
| Decision | What it addresses | What it does not establish |
|---|---|---|
| Local substantial-damage determination | Whether the proposed repair meets the community’s floodplain rule and current standards | Insurer valuation, policy total loss, or grant eligibility |
| Increased Cost of Compliance (ICC) | A specific NFIP policy mechanism for certain eligible flood losses with required compliance work | Ordinary code-upgrade coverage on every homeowner policy or a universal payment amount |
| Severe Repetitive Loss (SRL) designation review | Whether FEMA’s administrative property-status information should be reconsidered based on submitted documentation or completed mitigation | A claim appeal, automatic removal of a surcharge, code determination, or grant award |
FEMA’s ICC material describes one policy-specific route for eligible compliance costs. Check the current policy, forms, local determination, eligible work, deadlines, limits, and insurer instructions before counting any amount. Do not generalize ICC to ordinary homeowner insurance, unrelated upgrades, or Canadian coverage.
The June 2025 NFIP Claims Manual says a policyholder may ask FEMA to review documentation if they believe a property’s SRL claim history or market value is inaccurate, or after mitigation that may change future flood potential. That is a narrow administrative status route. It does not decide whether the present repair scope complies with local rules or whether an insurer must pay a particular claim.
Community code funding is not a homeowner upgrade grant
After a qualifying major-disaster declaration, FEMA’s Section 1206 guidance describes conditional Public Assistance reimbursement to eligible state, local, tribal, or territorial government applicants for certain disaster-related code administration and floodplain enforcement. Examples include inspections and substantial-damage determinations, letters, and appeals. Eligibility, applicant responsibility, documentation, disaster terms, and the applicable cost share govern.
That reimbursement supports government administration. It is not a direct payment to an individual homeowner for a new roof, raised foundation, electrical upgrade, or other required construction. FEMA’s Section 1206 FAQ explains the government-applicant and documentation boundaries. Keep community inspection funding separate from an insurer’s policy decision, a homeowner’s compliance cost, and any household assistance program.
Ask who owns each part of the answer
A permit office or floodplain official can identify the adopted rule, the trigger, and the required approval record. A designer or engineer can show how that rule changes drawings and specifications. A contractor can price labor, materials, demolition, access, and sequencing. An insurer can explain whether the policy contains a code or ordinance provision and what documentation it requires. A public-program administrator can decide whether a specific assistance route applies.
A useful project file keeps those answers separate. For each proposed upgrade, record the location, authority, requirement, supporting document, estimate line, payer being asked, and unresolved question. If an insurer excludes or limits a line, ask which policy wording or decision applies. If the estimate includes an upgrade without a local determination, ask for the trigger before accepting it as mandatory.
Consider the cost effects beyond materials
Required work can add design or engineering, permits, inspections, demolition, specialized materials, structural changes, utility relocation, labor, site preparation, access arrangements, and schedule delay. A floodplain requirement can also change foundation work, elevation, floodproofing, relocation, or temporary living. These are possible cost drivers, not a package that applies to every loss.
Ask the contractor to identify quantities, assumptions, exclusions, and the condition that would create a change order. Ask whether the price covers only the compliance work or also restoration needed to reach it. Compare the permit-driven scope with like-kind repair and optional betterment so that an insurance question does not obscure the total amount the homeowner may need to finance.
Canada and other local rules require local verification
The U.S. NFIP examples above do not create a Canadian rule. Canadian building codes, floodplain restrictions, permits, insurance endorsements, and assistance programs depend on the province, territory, municipality, property, and actual policy. Ask the local authority what it requires and the insurer what the contract recognizes. Do not infer that a U.S. substantial-damage threshold, ICC benefit, or SRL process applies to a Canadian home.
Questions to take to the next meeting
- Which authority has made the determination, and can I have it in writing?
- What local code, permit, floodplain rule, or project fact triggers each added line?
- What value and repair-cost method were used, and does a stricter or cumulative local rule apply?
- Which work is like-kind restoration, required compliance, or an optional improvement?
- Which design, engineering, permit, inspection, demolition, utility, and temporary-living costs are included?
- Does a policy-specific code provision apply, and what current conditions, limits, or deadlines govern it?
- Is any public reimbursement for government administration being incorrectly treated as household funding?
- What documentation would change the estimate or decision?
There is no single code-upgrade percentage that answers every rebuild question. The dependable result is a documented local requirement, a scope that separates physical work from optional choices, and a distinct decision from each insurer or program asked to pay.