
A termite “bond,” warranty, or protection plan is a contract description, not a universal product. It may provide inspection, monitoring, retreatment, damage-repair coverage, or some combination. Current U.S. market observations report annual termite service around $200–$400 in some provider data, but plans vary in price, terminology, exclusions, and service obligation. Canadian contracts may use different language and should be read under the terms that apply locally.
Separate the four promises
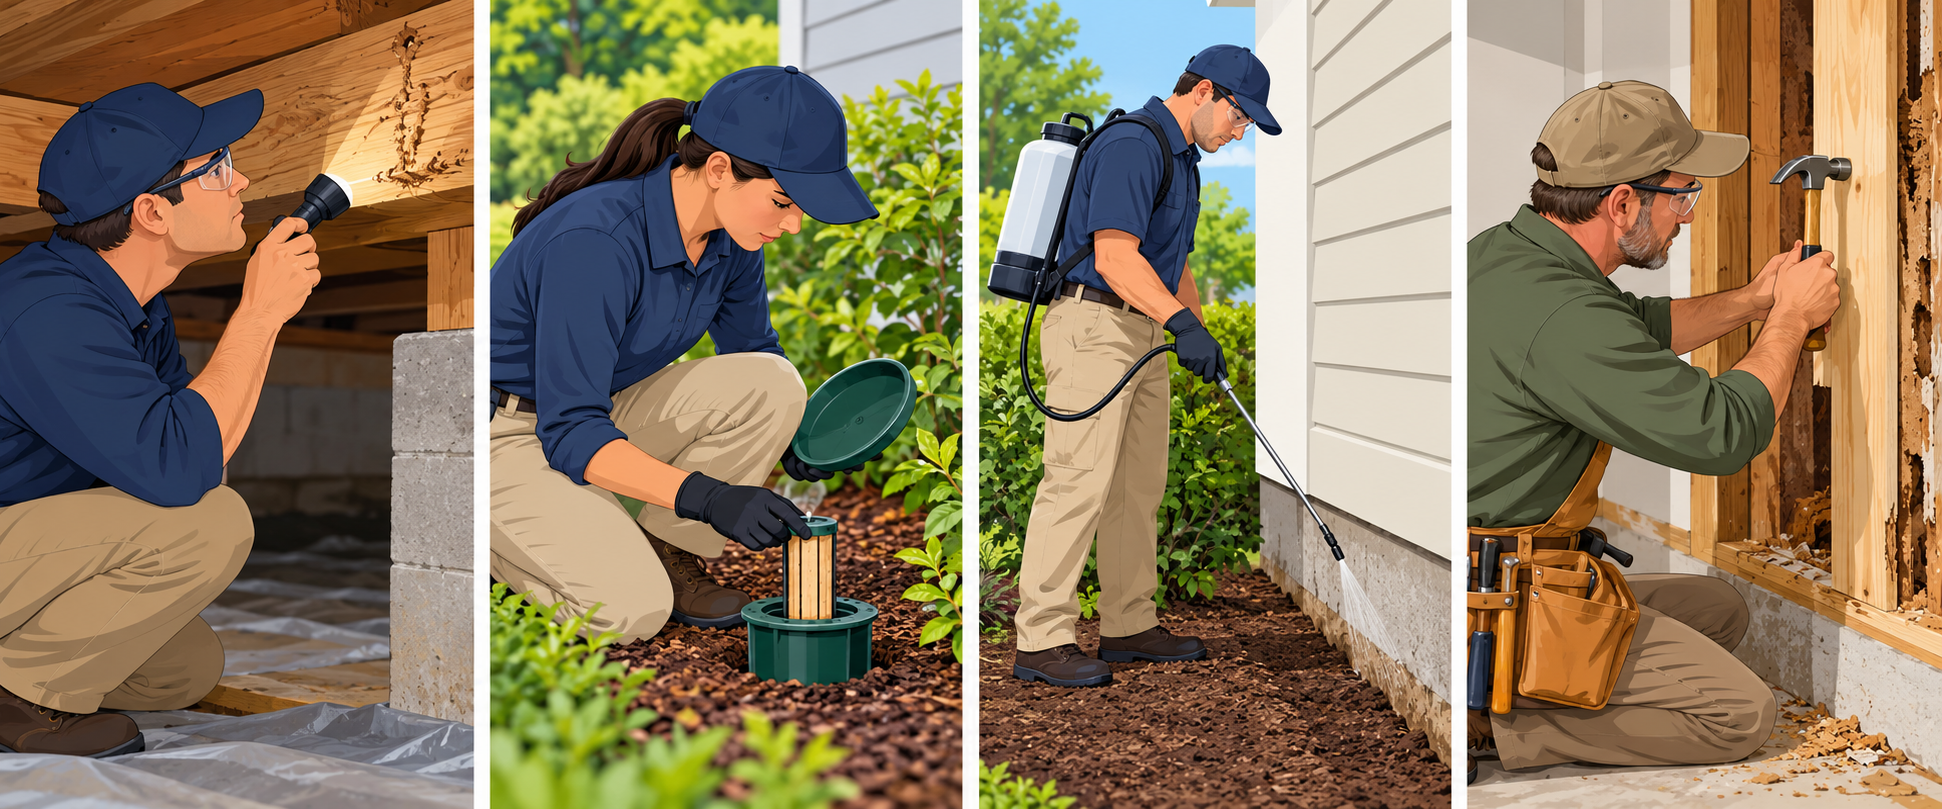
Ask which of these the plan actually provides:
- Inspection: a periodic search for signs, not necessarily treatment.
- Monitoring: stations or scheduled observations that may lead to action.
- Retreatment: a promise to treat recurring termites under stated conditions.
- Damage repair: a limited promise to pay for some qualifying damage.
An inspection agreement is not automatically a retreatment guarantee. A retreatment guarantee is not automatically insurance or structural repair coverage. Put the exact promise beside its price.
What to compare before renewal
| Contract question | Why it changes value |
|---|---|
| Was an initial treatment required? | A plan may not cover a property with untreated or pre-existing activity |
| What species and areas are covered? | Specialty or inaccessible areas may be excluded |
| How often are inspections or station visits performed? | Frequency affects both cost and the chance of early detection |
| What triggers retreatment? | Evidence, a report, or a provider’s discretion may lead to different outcomes |
| Is damage coverage included? | It may have exclusions, caps, proof requirements, and maintenance conditions |
| What must the homeowner maintain? | Leaks, access, landscaping, or construction changes may affect coverage |
| What happens on cancellation or nonrenewal? | The future risk and inspection history do not disappear when the contract ends |
| Is the agreement transferable? | Buyer transfer may have notice, inspection, and fee conditions |
EPA consumer guidance recommends asking what a guarantee covers and whether annual inspection charges apply. It also warns that the guarantee is only as reliable as the company offering it. That is a reason to read the actual terms, not a reason to assume every provider is unsuitable.
Do a multi-year comparison
Calculate the first-year cost, then the cost in years two and three. Include the initial treatment, annual renewal, scheduled inspections, station replacement, extra visits, and any required repairs. Compare the plan with self-funded inspections and the cost of a possible retreatment, but do not treat an uncertain risk as a guaranteed loss.
Ask whether the plan reduces or transfers a specific risk. Monitoring may be valuable when early detection is difficult. Damage coverage may be valuable only if its exclusions and limits match the property. An inexpensive plan that excludes the relevant structure or requires maintenance you cannot perform is not necessarily economical.
“Termite bond” is not a standardized scope
The same phrase can mean different things across markets. Do not assume it includes fumigation, drywood termites, subterranean termites, structural repair, resale transfer, or a fixed number of visits. Ask the provider to define the term in plain language and provide the full written agreement before payment.
What remains outside the plan
Moisture correction, structural engineering, framing replacement, flooring, drywall, and finish work may be excluded. A plan also cannot establish that visible damage is active or structural without the appropriate inspection. Read termite damage repair cost when a treatment proposal identifies weakened wood.
Compare coverage with the risk you actually have
A monitoring-only plan may make sense when early detection is valuable and the property can be inspected regularly. A retreatment plan may matter when the provider is responsible for responding to renewed activity. Damage-repair coverage sounds broader but may exclude pre-existing damage, inaccessible areas, moisture, maintenance failures, species, structures, or repair categories that matter to the homeowner.
Ask whether the contract covers the house, garage, detached structures, additions, crawlspaces, and areas previously treated. Ask whether inspection is visual, whether stations are serviced at a defined frequency, and whether the provider must find activity before it has an obligation to act.
A Florida disclosure example
Florida Statute §482.227 requires a WDO treatment contract’s first page to state in bold whether it offers repair plus retreatment, retreatment only, or no warranty or guarantee, and whether limitations or exclusions apply. This is a Florida-specific disclosure rule; it does not set a plan price, minimum term, or required coverage elsewhere. For any location, compare the written contract itself with the salesperson’s description.
Transfer, renewal, and claim terms
If the home may be sold, confirm whether transfer is allowed, what fee or inspection applies, whether the buyer must qualify, and whether coverage continues unchanged. At renewal, compare price, visits, monitoring, exclusions, caps, claim deadlines, and homeowner duties with the previous term; “transferable” and “renewable” do not mean automatic or unchanged.
For a retreatment or repair claim, ask how to report new activity, what records or inspection are required, how quickly the provider responds, who selects the repair contractor, and whether payment is capped. Confirm how moisture, access, landscaping, or renovation duties affect the promise, and keep a reserve for excluded repairs. The contract—not the annual fee or salesperson’s assurance—defines the protection.
Put a three-year price beside the written promise
Using the broad U.S. observation above, a plan priced at $200–$400 per year would total about $600–$1,200 over three years in renewal fees alone. That calculation excludes the initial treatment, inspections or stations billed separately, repairs, taxes, transfer fees, and any change in renewal price. It is arithmetic on an approximate market observation, not a quote or guarantee that a particular plan costs that amount.
Build the comparison from the contract:
- initial treatment and setup, if required;
- year-one plan fee and each renewal;
- included inspections or station visits;
- extra callbacks or station replacement;
- damage-repair limits and deductible, if any;
- conditions the owner must meet to keep coverage active;
- transfer or cancellation fees.
Then compare that total with the actual service promised. If the plan only inspects, the financial outcome is earlier information. If it promises retreatment, identify the event that triggers service and whether there is another charge. If it includes damage repair, compare its cap and exclusions with the type of loss the homeowner is trying to manage. There is no useful break-even calculation if the events and obligations are undefined.
Stress-test the promise against three outcomes before paying. If no new evidence appears, what inspections or monitoring does the fee buy? If termites return, which areas and species qualify for retreatment, and who pays for another visit? If damage is reported, what proof is required, what repair limit applies, and which building components or finishes are excluded? A provider can answer each question from the contract; a broad “protection” label cannot. This check is especially useful when comparing an annual inspection plan with a contract that also promises retreatment or repair, because the higher fee may buy a narrower or more conditional benefit than the name suggests.
The three-year total is a contract cost, not an estimate of avoided damage. If treatment is charged only after monitoring finds activity, include the stated retreatment fee in a separate conditional line rather than assuming either a free response or a future claim. If renewal prices can change, compare the actual written year-by-year amounts and repeat the calculation before each renewal.
When two plans include different visit counts, note the annual price and the number and type of included visits separately. A simple fee-per-visit calculation can normalize the schedule for comparison, but it cannot measure inspection quality or make a retreatment promise equivalent to monitoring. Read the service descriptions before choosing by that calculation.
Before relying on a renewal, get changes in price and terms in writing. If a leak, renovation, inaccessible area, or new damage has changed the property, ask whether coverage is affected. If you cancel, preserve service records; ending a plan does not remove an existing building risk.
Bottom line
Compare the specific promise—inspection, monitoring, retreatment, or damage repair—with its price, conditions, exclusions, transfer, and renewal terms. In Florida, use the required first-page disclosure as a starting point for reading a WDO contract; in every jurisdiction, verify the actual written obligation rather than relying on “bond” or “warranty” as a standardized label.