
Heritage assistance can change which conservation work is affordable, but its headline amount may arrive after design, approval, construction, or tax filing. Build a gross project budget from local, itemized scopes first. Then check whether the owner, property, and proposed work meet a specific program’s rules and when any support could actually be used.
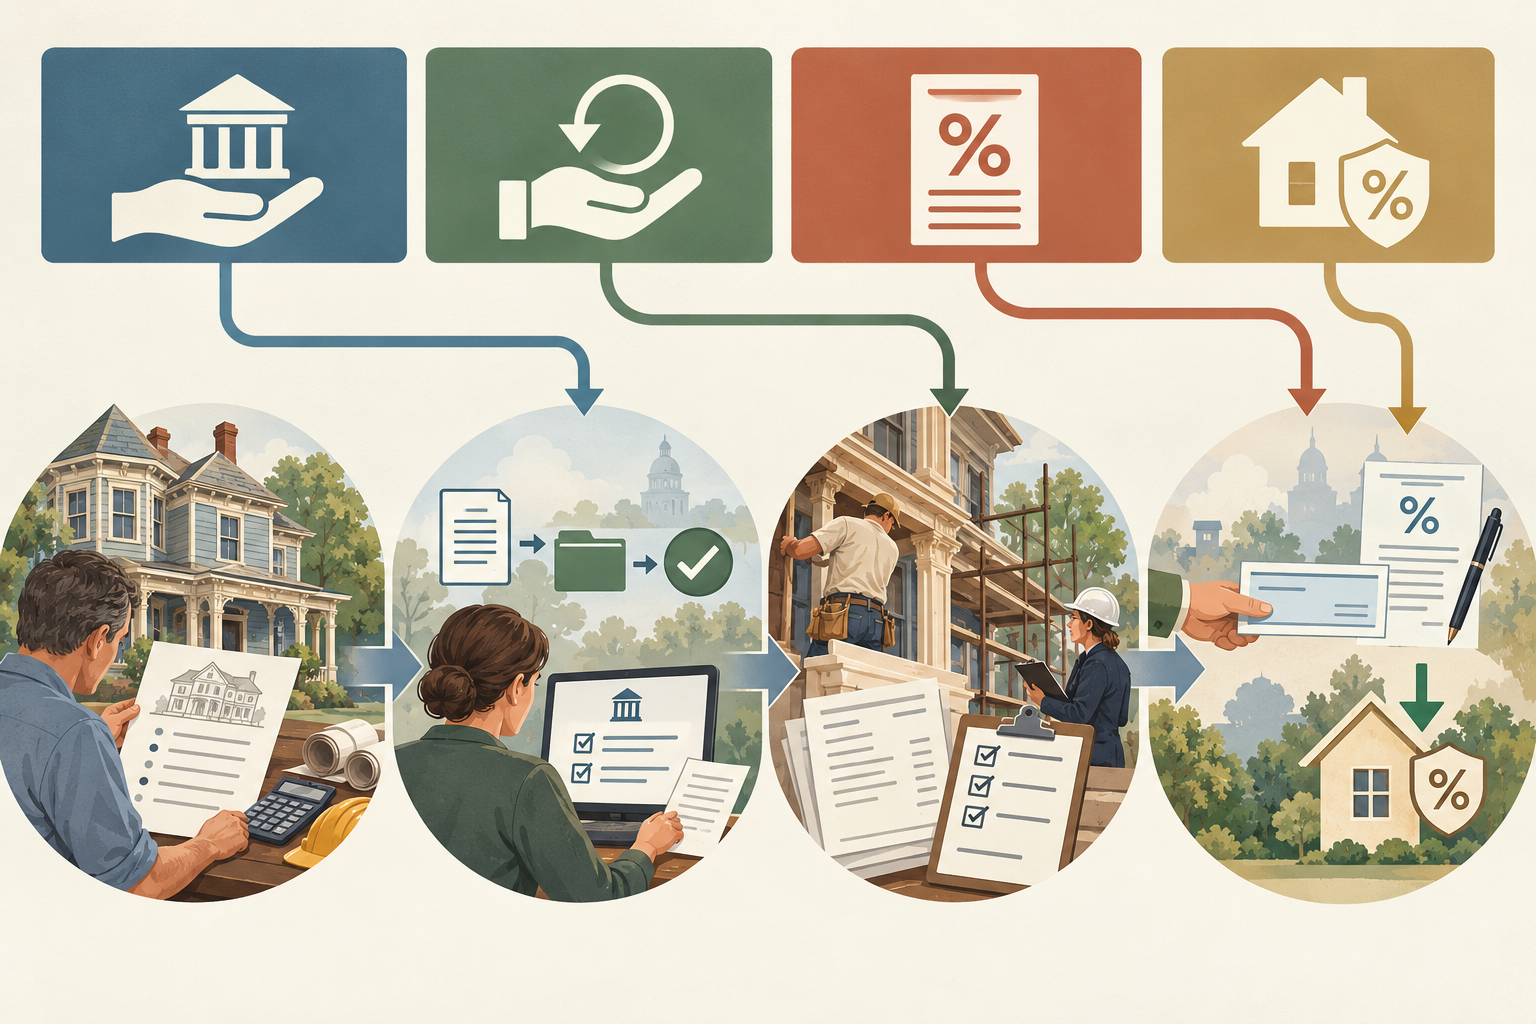
A designation, an eligible work item, an approved application, permission to start, a completed project, a tax claim, and a payment are separate things. A program page cannot determine an individual property’s eligibility or guarantee funding. Treat the examples below as ways to ask better questions, not as a directory or an expected benefit.
Start with the complete cost of work
Ask for a written conservation scope before estimating assistance. Separate:
- investigation, condition reports, drawings, professional fees, and application charges;
- the repair or restoration work itself, by feature, elevation, or building system;
- work that may be ineligible, such as routine maintenance, a repairable original feature’s replacement, or new construction;
- access, protection, temporary weatherproofing, permits, and finish restoration;
- owner-selected upgrades and contingency for conditions that are still unknown.
A detailed estimate helps the program administrator assess the proposal and gives you a usable price if the application is reduced or declined. Some programs accept or require specialist reports, itemized bids, photographs, plans, or samples. Do not assume those preparation costs are eligible for reimbursement; check the actual program terms.
Keep the gross contract amount visible. If a $70,000 scope contains $50,000 of proposed slate-roof conservation and $20,000 of unrelated interior work, the quote should identify those lines separately. The roof and room work may follow different eligibility rules, even when one contractor prices both.
Separate grants, tax credits, and property-tax relief
The word “assistance” can describe benefits with very different cash-flow effects:
| Mechanism | What it may do | Budget question |
|---|---|---|
| Grant or matching grant | Pay a stated share of approved, eligible work under program conditions | Is payment made before work, in stages, after inspection, or after closeout? What owner match and excluded costs remain? |
| Reimbursement | Repay some eligible expenses after the owner pays them | Can you carry the full cost and wait for review? Which receipts and completion records are required? |
| Income-tax credit | Reduce a tax liability after the project meets program and tax rules | When can you claim it, what tax year applies, can it be carried forward, and which professional can confirm the result? |
| Property-tax relief | Reduce or refund a portion of eligible property taxes under local rules | Is a local program in force, what agreement is required, and when does the tax bill change? This does not pay a contractor’s invoice. |
Program labels do not settle payment timing. Ask the administrator to identify the controlling event in writing: application, approval, receipt of a subsidy, permission to start, completed work, final inspection, certification, or tax filing. Do not use a tax credit or property-tax reduction as cash available for a deposit unless the relevant authority and your tax professional confirm how and when it can be used.
Local examples show why status and timing matter
A federal U.S. credit may not fit an owner-occupied home
The National Park Service’s federal rehabilitation tax credit concerns qualifying historic buildings in income-producing use. Its eligibility page says an owner-occupied private residence does not qualify. Rental residential and some business portions may qualify in certain circumstances if the building and project meet the other program tests. A homeowner should not subtract this federal credit from a personal-home repair budget based only on the property’s age or historic listing.
New York has a separate owner-occupant program
New York State’s Historic Homeownership Rehabilitation Tax Credit is a state income-tax credit equal to 20% of qualified rehabilitation expenses, subject to its applicant, property, location, and work tests. The owner must live in the home; the property must meet the listed register or district conditions and qualifying census-tract rule; the state page also lists minimum qualified expenses and an exterior-work share. Projects must be approved before work begins.
The page describes a second step after construction: submit a Part 3 application with photographs and final costs, receive a Certificate of Completion, then claim the credit on the New York income-tax return for the tax year in which that certificate is issued. This sequence means that a potential credit is not automatically cash for the contractor during construction. Confirm current program requirements and tax treatment before relying on it.
Toronto’s 2026 grant is tied to designated features and eligible work
The City of Toronto’s 2026 Heritage Grant requires the property to be in Toronto and designated under Part IV or Part V of Ontario’s Heritage Act; a district property must contribute to the district’s heritage value. The work must relate to identified heritage attributes or meet the page’s district criteria. The page lists repair of original windows and doors, masonry, woodwork, and slate roofs, but excludes replacement of repairable original windows and routine maintenance.
For a comprehensive repair or restoration of an original slate-roof assembly, the page lists a maximum grant of 50% of costs up to CAD $20,000. It also asks for detailed cost estimates by item. The page gives November 7, 2026, by 5 p.m. as the deadline for that cycle; future intake dates and funds can change. Its public page does not establish an individual award or payment date, so confirm both with the City.
Montréal’s page has a different start-work condition
Montréal’s support-program page was last updated on February 28, 2025. It lists assistance percentages and caps that vary by property category, not one citywide rate. The page says work may not be completed or started before receipt of the subsidy. It also lists two licensed-contractor bids and proof that the owner can finance the total work cost among the application materials.
Because the page is dated, ask the City to confirm that the program is open, which property category applies, and what “receipt of the subsidy” means for the current project before scheduling work. Do not quietly replace that wording with “application approved” or assume that an approval letter authorizes construction.
Ontario property-tax relief is not construction cash
Ontario municipalities may choose to establish a local heritage-property tax-relief program by bylaw. The provincial page describes relief between 10% and 40% of eligible property taxes for qualifying designated property with a heritage conservation agreement. A municipality’s adoption and extra criteria determine availability. This changes a property-tax obligation; it is not a grant against the contractor’s bill.
Ontario’s separate municipal tax-grant guidance also describes locally defined tax-back grants and terms that can apply to sale, transfer, or unpaid taxes. Read the actual bylaw and agreement for maintenance, inspection, transfer, or repayment conditions. These Ontario examples do not establish a benefit in another municipality or province.
Turn a published maximum into a bounded scenario
Suppose the Toronto example above is relevant to the property and the owner receives approval for $50,000 of eligible original slate-roof work. The published 50% share would calculate to $25,000, but the page’s CAD $20,000 cap would limit the possible grant to $20,000. If a separate $20,000 bathroom scope is not eligible, the total quoted work remains $70,000.
This arithmetic is only an upper-bound illustration using the City’s published cap. It does not predict eligibility, approval, available funds, payment timing, or actual roof price. Until the City confirms the award and payment terms, keep the full $70,000 gross scope in the cash-flow plan. If a CAD $20,000 grant is eventually paid, the final project cost would still include the excluded $20,000 room work, any owner match, application or professional costs, and any other ineligible expenses. Do not treat the maximum as cash in hand.
Check eligibility and start-work rules before committing
Before signing a construction contract or setting the start date, ask the program administrator and relevant local authority:
- Does the owner qualify, and does the property’s exact designation or district status meet the program’s definition?
- Which attributes, rooms, elevations, or work items are eligible? Are maintenance, replacement, additions, or energy upgrades excluded?
- What report, photographs, drawings, itemized bids, samples, fees, or owner-match evidence must accompany the application?
- Must the application be submitted, approved, or funded before any work starts? Is the trigger different for emergency stabilization?
- Are heritage consent, a building permit, or trade approvals separate from the assistance decision?
- Is the benefit a grant, reimbursement, income-tax credit, or property-tax change, and when can the owner actually use it?
- What happens if the project scope changes, eligible costs are reduced, or funding is unavailable?
- Does a conservation agreement require continued maintenance, retention of features, access for inspection, notice before transfer, or repayment in stated circumstances?
Get answers in writing and keep the version and date of the program terms with the bids. Grant approval is not permission to alter a protected feature; heritage consent or a building permit does not prove that the related expense is eligible. Likewise, an income-tax credit is not the same as a cash grant.
Keep the project viable without the benefit
Build a conservative plan with the full priced scope, the owner’s required contribution, application and professional costs, excluded work, and the longest plausible time before any confirmed payment or tax filing. Use only an approved amount and written payment terms when deciding whether to reduce cash reserves or release an optional phase. If the award is delayed, reduced, or unsuccessful, the owner should be able to choose a smaller eligible scope, phase work, or defer nonessential improvements without leaving a necessary safety or water-control problem untreated.
For work that may affect safety or active damage, ask the responsible professional and program administrator how to stabilize the condition while preserving eligibility where possible. Do not delay necessary qualified safety action on the assumption that assistance will arrive, and do not start work that a program expressly prohibits before its required trigger. The property, written program terms, and appropriate professional advice determine the next step.