
“Permanent foundation” can mean different things in casual construction language, local regulation, title records, and lending. A system that satisfies one purpose may not automatically satisfy another. Before budgeting a retrofit, define whether the goal is structural stability, replacement of failing supports, a local approval, a foundation certification, a title change, or a lender’s specific eligibility requirement.
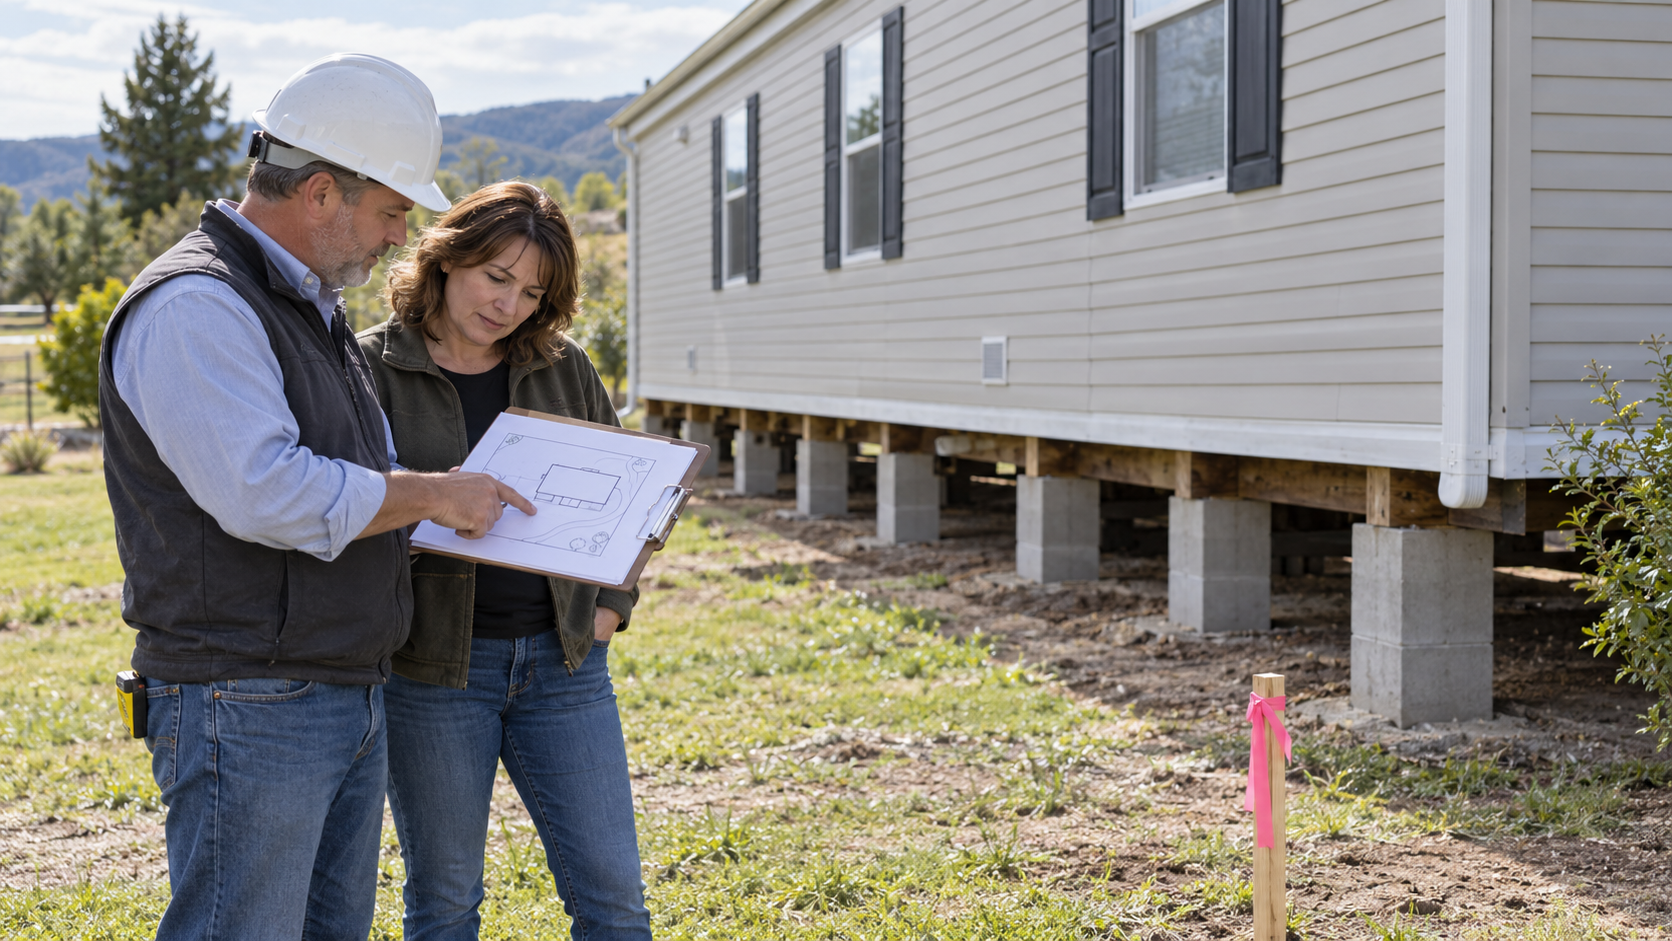
What the project may include
A retrofit can involve site investigation, soil or bearing information, footings, piers or perimeter support, a crawl-space or basement configuration, anchorage, connection between the home and foundation, drainage, access, engineering, permits, and inspections. The existing chassis, section arrangement, home condition, and installation history affect what is feasible.
HUD foundation guidance addresses compatibility between the home, site, soil, stability, and environmental loads. U.S. installation standards also distinguish foundations, piers, footings, anchoring, drainage, and final leveling. These sources support the need for a designed system; they do not provide one universal retrofit detail or price, and they do not establish Canadian requirements.
Why homeowners consider it
The reason may be recurring settlement, inadequate or deteriorated supports, a planned addition, a high-risk site, a sale or refinance requirement, or a desire to change the home’s long-term support. A permanent-foundation project may solve one structural or transaction problem while leaving documentation, zoning, title, insurance, or lender requirements unresolved.
Ask the lender, title professional, building authority, or engineer for the exact document or inspection they require before construction begins. Do not pay for a foundation described only as “permanent” if nobody can state the acceptance criteria.
Build a comparable quote
Request separate lines for investigation, survey, engineering, excavation, soil work, footings, walls or piers, anchorage, drainage, lifting or temporary support, utility and access changes, permits, inspections, and restoration. Clarify whether the quote includes removal of existing supports, correction of settlement, skirting, stairs, vapor or moisture control, and certification paperwork.
Site access, groundwater, rock, frost, slope, flood or seismic exposure, and the distance to staging can dominate the budget. The home may need to be temporarily supported while work proceeds. A quote based on a generic site-built foundation is not necessarily suitable for a chassis-supported home.
Decide with the whole obligation visible
Compare the retrofit with repair of the existing support, buying an already-installed home, or another project that achieves the same objective. Keep U.S. and Canadian requirements and prices separate. FHA, conventional-lender, provincial, state, and local rules are not interchangeable, and a foundation retrofit does not guarantee a financing or property-classification outcome.
Use a qualified local professional for design and approval. The useful cost number is the complete accepted system—including engineering, site work, connection, inspection, and documentation—not the concrete or pier line alone.
Model the complete retrofit, not the concrete line
As a U.S. planning scenario, a homeowner might model $6,000 for engineering and documentation, $25,000 for excavation and foundation work, $12,000 for connection, access, and drainage, and $4,000 for inspection and closeout: $47,000 before unusual soil or site constraints. A separate Canadian scenario might use CAD 8,000 + CAD 32,000 + CAD 15,000 + CAD 5,000 = CAD 60,000. These are transparent examples, not a national price range, lender quote, or certification guarantee.
The decision changes if the property needs a new utility route, retaining work, frost protection, flood adaptation, or major lifting. Request a design basis, inclusions, exclusions, and approval path in writing. Compare the accepted retrofit with the value it unlocks rather than assuming a permanent foundation automatically changes the home’s legal or lending status.
Define the objective before selecting a foundation
Write down the result the retrofit is supposed to achieve: stable support, correction of existing settlement, a lender’s written foundation requirement, a title or tax review, a new addition, or preparation for a sale. One project may serve several goals, but the professional needs the actual acceptance criteria before designing. Ask the lender, title professional, local authority, or engineer to identify its document, inspection, connection, or approval standard in writing. Do this before excavation because a foundation that is structurally adequate may still fail a separate transaction requirement.
Separate three questions in the budget. The first is whether the structure and site can support the home. The second is whether the work meets the applicable local and installation requirements. The third is whether the result is accepted for a particular title, tax, insurance, or loan purpose. These questions can involve different professionals and should not be hidden inside a bid labeled “permanent foundation.” Do not assume that one certificate changes the home’s legal classification or guarantees a financing outcome.
Ask the designer to inspect the existing home, frame or chassis, foundation, soil and drainage, section connections, additions, utilities, access, and prior alterations. The retrofit may require temporary support, lifting, excavation, foundation walls or piers, connection hardware, moisture management, utility changes, engineering, inspections, and restoration. A basement or crawl-space conversion adds excavation and water-management questions that are not captured by a foundation-only unit price.
Compare retrofit paths with the same goal
Possible alternatives include repairing existing supports, redesigning part of the support system, installing a new engineered foundation, or purchasing a home that already satisfies the transaction requirement. Sometimes the owner needs a targeted correction and not a full conversion. Ask the engineer what each alternative solves, what it leaves unresolved, expected future access, and which permit or lender criterion it addresses. If the objective is a loan or sale, compare the project cost with the current written acceptance requirement rather than relying on a broker’s or contractor’s verbal description.
A repair may have a lower initial cost but leave documentation or eligibility questions open. A broader retrofit may cost more yet solve recurring settlement and make future inspection easier. Buying a replacement may avoid the construction disruption but require a new site, move, utility work, or transaction cost. Build a table with total construction, professional and approval fees, temporary housing, lost use, future maintenance, and evidence of acceptance. Keep the alternatives separate and state any unknown lender, tax, insurance, or code assumption.
Understand the site and construction sequence
The bid should establish what is known about bearing soil, groundwater, slope, frost, flood or seismic exposure, drainage outlet, excavation access, and staging. Ask whether a geotechnical report, survey, engineered drawing, or test excavation is required. If it is, price that discovery phase before treating the construction amount as fixed. Ask what change-order trigger applies if the site reveals rock, unstable fill, water, or an incompatible existing support.
Request a sequence showing temporary support, utility protection, excavation, foundation construction, home-to-foundation connection, drainage and moisture control, inspection, backfill, restoration, and final documentation. Identify who confirms each concealed stage before it is covered. Where the home must be lifted or temporarily disconnected, establish who bears risk for damage to plumbing, electrical, fuel, section joints, stairs, skirting, and finishes.
The quote should list design and engineering, material and labor, equipment, excavation and haulage, foundation, anchor or frame connection, insulation or moisture controls if required, permit, inspection, utility change, temporary support, debris, and restoration. It should state the home and site assumptions, applicable design standard, warranty, exclusions, and acceptance documents. A complete estimate can be compared with another; a lump-sum “permanent” label cannot.
Keep geography and program rules distinct
U.S. HUD foundation guidance and lender program criteria are not automatically Canadian rules. Ontario and British Columbia examples demonstrate that site and certification responsibility can differ by province. Confirm the state, province, municipality, local authority, and financing program before relying on a detail or certificate. For a manufactured home built without a permanent chassis, the July 2026 statutory definition change does not itself establish a foundation design or loan qualification; ask the lender and local authority what standards currently apply.
Budget for acceptance and future use
After work, request engineering closeout, permit and inspection records, photographs of concealed connections, warranty information, and any lender-specific certificate. Put delivery of those items in the contract. Keep a contingency tied to identified site uncertainties rather than an arbitrary percentage. If the foundation is being built only to satisfy a transaction, obtain confirmation that the proposed documents and design will meet the recipient’s criterion before work starts.
The comparison is complete only when it shows the structural objective, site conditions, approval path, full installed system, expected disruption, and accepted records. That approach does not make the final price predictable before investigation; it makes the unknowns visible enough to decide whether a retrofit is worth pursuing.
Keep flood compliance and foundation design distinct
For a home in a mapped flood-risk area, ask the insurer and local floodplain official which foundation, anchoring, permit, and inspection rules apply to this property. FEMA’s NFIP materials discuss manufactured-home eligibility and rating inputs, but a policy condition is not an engineered foundation design. Increased Cost of Compliance can be relevant after a qualifying insured loss and a local substantial- or repetitive-damage determination; it is not a general retrofit grant or a source of foundation pricing. Obtain the local determination and a qualified design before comparing bids.
Check the transaction timeline
If a retrofit is tied to closing, refinancing, or insurance renewal, map the design review, permit, construction, inspection, certificate, and lender or insurer review against the deadline. Ask the recipient how long it takes to review final documents and whether it must approve the design before work begins. A technically complete foundation may still miss a deadline if the required inspection or paperwork is scheduled afterward.
Price temporary housing, extension fees, interest, or a delayed sale where relevant. Confirm the conditions for extending a commitment in writing. This timeline can change whether a retrofit is practical compared with another property or transaction path.